Polish company Netwise S.A. joins the collana Group
Home / Polish company Netwise S.A. joins the collana Group The
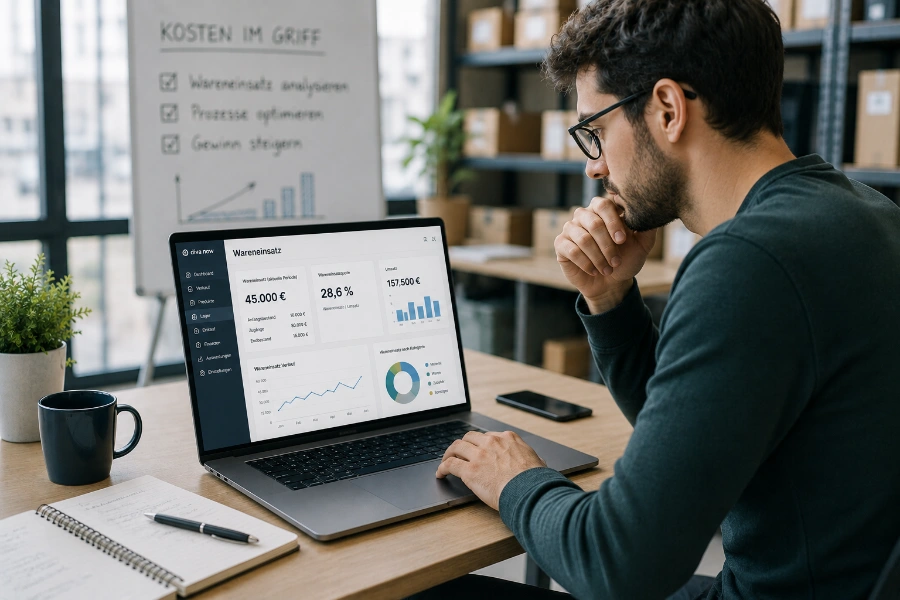
Cost of goods sold is a key financial indicator in accounting and plays a crucial role for businesses in the retail sector, manufacturing and other industries. By calculating your cost of goods sold accurately, you can analyse your costs, optimise them and thereby increase your profit.
In this article, you’ll find out everything you need to know about calculating the cost of goods sold, its definition, the cost of goods sold ratio, and practical tips on how to optimise it.
Cost of goods sold refers to the cost of goods sold or materials used during a specific period. It is a key financial indicator in accounting and is recorded in the profit and loss account (P&L).
The calculation is carried out using the following formula:
Cost of goods sold = Opening stock + Purchases – Closing stock
It provides information on how much was spent on sales or production.
The cost of goods sold is crucial for cost control, pricing and calculating gross profit within a business. An accurate calculation helps to assess profitability.
The cost of goods sold ratio represents the relationship between the cost of goods sold and turnover. It is used to assess a company’s efficiency and to make industry comparisons.
With the ERP solution collana diva now Companies can efficiently manage their stock, production and material costs. Automated processes and real-time data help to reduce the cost of goods sold in the long term.
Cost of goods sold refers to the costs incurred by a company for goods sold or materials used in production during a specific period. This key figure is crucial for tracking the cost of materials and assessing the efficiency of resource utilisation.
The cost of goods sold is usually calculated in the profit and loss account (P&L) and is recorded on the debit side of the P&L account. The definition covers both the opening stock of goods and additions, as well as the closing stock at the end of the year.
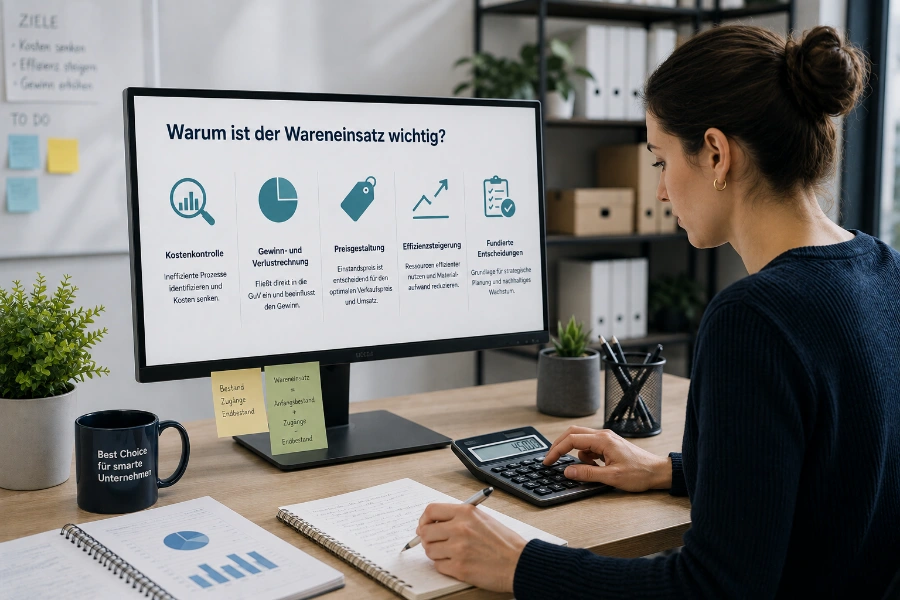
The cost of goods sold is not just a figure, but a basis for business decisions. It is essential to calculate the cost of goods sold correctly, as:
Cost control: By analysing the costs of goods and materials, companies can identify inefficient processes.
Profit and Loss Account (P&L): The cost of goods sold is recognised directly in the profit and loss account and affects the reported profit.
Pricing: The cost price is crucial for calculating the optimal selling price and, consequently, turnover.
Improving efficiency: With a clear overview of material costs, resources can be utilised more efficiently.
The basic formula for the calculation is:
Cost of goods sold = Opening stock + Purchases – Closing stock
This means:
Opening balance: The quantity of goods at the start of the period.
Additions: All goods added during the period.
Closing balance: The quantity of goods still in stock at the end of the period.
This formula forms the basis for calculating the cost of goods sold, whether in manufacturing companies or in the retail sector.
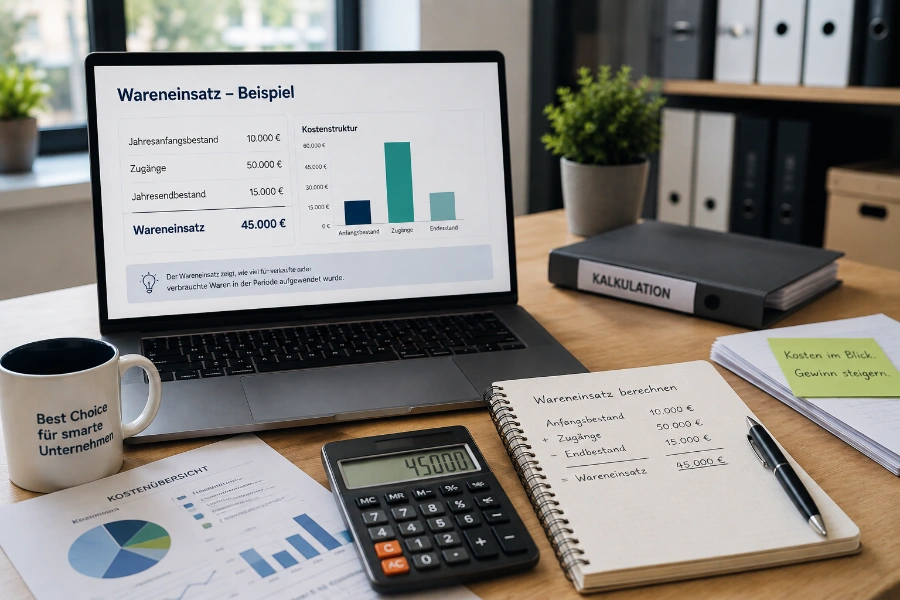
Let us assume that a company has the following figures, which we use to calculate the cost of goods sold:
The cost of goods sold is calculated as follows:
Cost of goods sold = €10,000 + €50,000 – €15,000 = €45,000
In this example, the cost of goods sold amounts to €45,000. This figure shows how much the company spent on goods sold or consumed during the period.
Cost of goods sold alone is often not sufficient to assess a company’s profitability. This is where the cost of goods sold ratio comes into play. It describes the ratio of cost of goods sold to turnover and is calculated as follows:
Cost of goods sold ratio = (Cost of goods sold / Turnover) × 100
A low cost of goods sold ratio indicates that a company has its costs well under control. Depending on the sector, the ratio stands at around 20–40 %, although manufacturing companies often have higher figures.
The profit and loss account provides information on a company’s performance during the financial year. The cost of goods sold is recorded on the debit side of the profit and loss account as cost of materials.
This item is important for calculating gross profit and thus determining the contribution to the company’s overall performance.
Optimising the cost of goods sold can therefore have a positive impact on the cost structure and profit. This raises the question: where, specifically, can companies start?
One optimised stock management is essential for minimising losses due to wastage, theft or stock becoming obsolete. Regular stock-takes help to keep track of current stock levels and enable a prompt response to potential sources of wastage. Efficient stock management can also save space and reduce storage costs.
Maintaining good relationships with your suppliers can reduce the cost of goods in the long term. Negotiate discounts, better payment terms or volume discounts to lower the cost price of your goods. A long-term partnership with reliable suppliers also ensures stable supply chains and reduces risks.
In manufacturing businesses, it is important to match output as closely as possible to demand. Overproduction leads to higher storage costs and tied-up capital. By carefully planning unit numbers and production volumes, companies can significantly reduce their costs for materials and storage.
Modern software solutions such as ours collana diva now enable the automation of inventory management and the calculation of the cost of goods sold. These solutions allow you to keep track of stock levels, goods received and goods dispatched in real time. Automated processes save time, minimise errors and thus help to optimise your overall cost structure in the long term.
The cost of goods sold relates to goods in the retail sector, whilst the cost of materials covers raw materials and consumables used in production.
The calculation is usually carried out at the end of a financial year, but may also be carried out quarterly or monthly.
The cost price of the goods forms the basis for calculating retail prices in order to ensure a profit margin.
Home / Polish company Netwise S.A. joins the collana Group The
The collana Group has launched the video podcast *CoreShift by collana*.
The Collana Group has reached a milestone that few others have
The ERP solution is specifically designed to meet the requirements of e-commerce and offers flexible scalability to support your growth.